
Open Jupiter, tell it you want to swap $SOL for $USDC, check the price, and press the button. From the user’s point of view, there is not much more to it.
So it’s only natural to assume that Jupiter is where the trade happens. In reality, Jupiter is closer to a search engine for liquidity. Its software looks across different places willing to take the other side of the trade, compares what they are offering, and sends the order toward the best route it can find. Its current system can choose among ordinary decentralized exchanges, proprietary automated market makers, or propAMMs, and a request-for-quote network where professional market makers compete to quote a price.
The user sees one interface and one price, while underneath it several very different kinds of markets can be competing for the same order.
So the person selling you $USDC might not be another user or a public pool funded by thousands of strangers. It could be a professional trading operation using its own money and pricing software, with no consumer-facing exchange and no pool into which you can deposit your own tokens. You never see most of that machinery; you just see the price that comes out of it.
A new analysis from DWF Ventures estimates that propAMMs account for roughly 15% to 27% of daily on-chain DEX volume. For one much smaller corner of the market, $SOL-to-stablecoin trades routed through Jupiter, DWF puts their share above 90%.
Those numbers come with an obvious caveat: DWF Ventures is part of DWF Labs, which is itself a crypto market maker and investor. Nonetheless, the exact percentage presented here is much less interesting than what the numbers describe. A form of trading that barely exists in most people’s mental model of DeFi has become large enough to shape how some of its busiest markets work.
That leaves crypto in a pretty strange place right now. The first generation of decentralized exchanges was built around the idea that markets could become more open by replacing professional dealers with public software. Anyone could see the pool, put money into it, and trade against it according to rules written into code. Now the professional dealer is coming back, and in some of the most liquid markets it seems to be very, very good at the job.
That would already be an interesting turn for DeFi. It becomes much more consequential when it’s happening at the same moment that Nasdaq, the London Stock Exchange, Robinhood, and Kraken are working on putting traditional stocks onto blockchain rails.
For years, finance has argued about whether Wall Street would move onto crypto’s infrastructure. But now, a harder question is starting to form behind it: what kind of market will be waiting there when it does?
The dealers are back in business
The original automated market maker was one of DeFi’s stranger inventions.
Imagine a currency booth with two piles of money, except there’s no dealer behind the glass. One pile contains $SOL and the other contains $USDC. Software connects the two using a formula. You put $SOL in and receive $USDC. As $SOL accumulates on one side and $USDC disappears from the other, the formula adjusts the price. Anyone can also contribute money to the booth and collect a portion of the trading fees.
That solved an enormous problem for early DeFi. A new market did not need to persuade a professional firm to keep buying and selling all day. It needed tokens, a smart contract, and people willing to deposit capital, and the market could run itself.
Running itself, though, isn’t the same thing as being good at trading.
Suppose $SOL is worth $100 inside the pool. News hits, centralized exchanges move immediately, and professional traders now value $SOL at $101. The pool doesn’t notice by itself, but an arbitrageur does. They buy the temporarily cheap $SOL and keep buying until the pool’s price catches up. The pool has learned that $SOL is worth $101 by selling $SOL too cheaply.
Academic work calls the problem loss-versus-rebalancing. The terminology is less important than what it means: a passive pool can repeatedly trade at yesterday’s price against people who already know today’s price. That’s a tolerable flaw when markets are calm, and trading fees compensate the people providing liquidity. It becomes an expensive problem when prices are moving quickly, and every stale quote is an invitation for serious and sizable arbitrage.
A propAMM reverses the arrangement. Instead of relying on thousands of outsiders to deposit tokens, a professional trading firm supplies its own inventory. Instead of waiting for trades to drag a formula toward the right price, its private software watches outside markets and continually changes what it is willing to buy or sell for. The transaction still settles on-chain, but the thinking that produced the price happens within the company.
It’s actually much closer to an electronic currency dealer installed inside a blockchain than to the vending-machine model that defined early DeFi.
It also explains why the word “proprietary” belongs in the name. Solana’s own explainer says today’s propAMMs are generally closed-source, their liquidity is not open for ordinary public deposits, and getting included by an aggregator is a permissioned process. Users can verify that a transaction happened on-chain without being able to inspect the system that decided what price to offer or why one market maker got the order.
From the old DeFi worldview, that can sound like regression. But, from the perspective of somebody trying to swap $SOL quickly and cheaply, the verdict is much less ideological.
Jump Crypto examined roughly 20 million propAMM fills from March and compared them with prices available across Binance, Coinbase, OKX, and Bybit. Its research found that the median $SOL–$USDC fill executed 0.72 basis points from its benchmark centralized-exchange midpoint, while 91.9% of fills were cheaper than Jump’s estimate for the lowest institutional centralized-exchange fee tier.
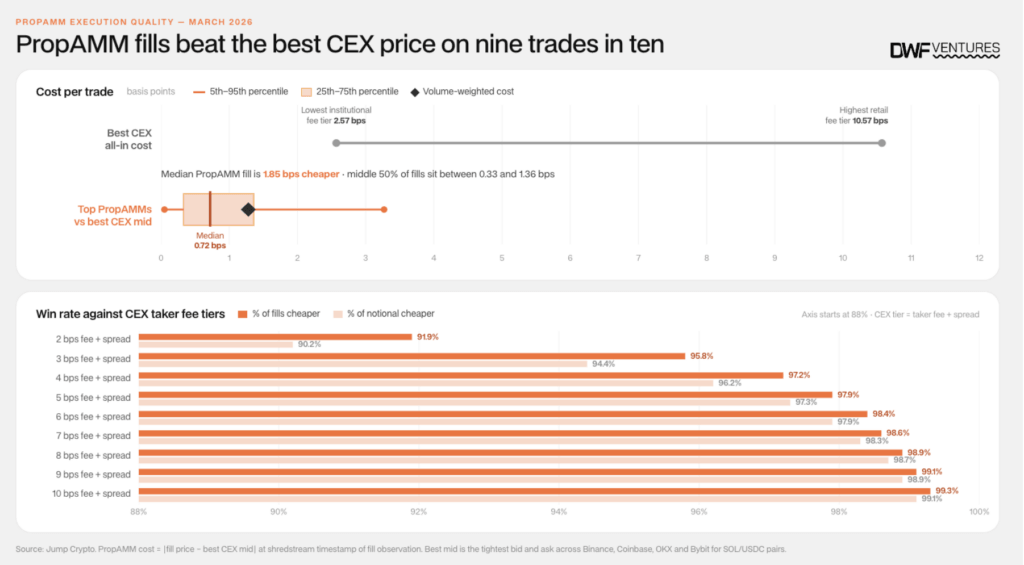
Jump is also a trading firm with commercial exposure to this market structure, so its study has its own incentives. Even so, the result helps explain why these venues are winning orders. Routers send them volume because, for certain trades, they can offer very good execution.
While this is a clear separation of both the mechanics and economics of decentralized trading, it’s also a cultural break with early DeFi. The first version of DeFi treated openness as part of the product itself. The pool was public, the code could be inspected, liquidity came from users, and the route from capital to transaction was visible enough that a technically competent person could follow most of it.
The newer version asks a more consumer-like question: if another system gives you a better price, how much of that machinery do you actually need to see? Once the answer becomes “not very much,” the exchange begins to disappear behind the interface.
DeFi is turning exchanges into routers
Solana was particularly hospitable to this model because professional market makers care obsessively about old prices. A firm offering $SOL at $100 doesn’t want that quote hanging around while the rest of the world trades at $101. Every extra moment gives somebody an opportunity to trade against the old price before the firm can replace it.
Ethereum still operates with 12-second slots. Solana, by comparison, reached its 300-millisecond target on Aug. 28, which CryptoSlate examined through the economics of stale-price arbitrage. The networks build and process transactions differently, so the comparison is not one-for-one, but the attraction is easy to understand. Professional market makers want to update prices as often and as cheaply as possible, and Solana’s own work on shorter slots explicitly points to lower stale-price exposure for liquidity providers and market makers.
You can reach the same destination another way, though. Instead of continually publishing every price on-chain, a system can ask professional firms for prices elsewhere and put only the winning trade on-chain.
That’s essentially what request-for-quote systems do. On 0x’s RFQ network, an application asks professional market makers for private off-chain prices, compares those offers with ordinary public AMM liquidity, and returns whichever route offers the better result. For highly traded pairs such as $USDC-WETH and WBTC-WETH, 0x says its RFQ liquidity beats AMM pricing about 52% of the time.
Jupiter is combining several versions of that on Solana. Public DEX liquidity, propAMMs, and professional quote systems all live behind the same interface, which means the trader no longer has to choose what kind of market to use before making the trade.
That may be the deeper and more important transition here. Old DeFi effectively told the user: here is a pool, now trade against it. But new DeFi is starting to say: tell me what you want, and I’ll figure out who should fill it.
Traditional finance already does this. When somebody submits an order to buy a stock, the customer usually doesn’t choose the exact market center or dealer that executes it: it’s the broker that routes the order. The SEC’s basic explanation of US equity execution describes brokers choosing among exchanges, electronic networks, market makers, and internalization depending on where they can obtain the best available execution.
PropAMMs aren’t just Wall Street dark pools transplanted onto Solana, and treating them that way would miss what makes the crypto version interesting. Blockchain settlement is observable, so the assets move across public infrastructure, and anyone can inspect the resulting transaction. What can remain private is the machinery around that transaction: the pricing model, the inventory decision, parts of the route, and sometimes the identity of the firm competing for the trade until execution occurs.
That creates a different definition of transparency. A financial market can expose ownership and settlement to public verification without exposing every part of price formation, and this distinction is becoming much more consequential as the assets moving through these systems stop being purely crypto assets.
Wall Street is coming just as DeFi changes course
Nasdaq said Thursday that its venture arm agreed to invest $100 million in Payward, Kraken’s parent company, while the two firms continue work on Nasdaq Equity Tokens. Nasdaq expects the framework to launch in the second quarter of 2027 and plans to connect it with Payward’s xStocks network.
The London Stock Exchange is moving in the same direction. On Sept. 1, LSEG announced a partnership with Payward around tokenized public equities and said it intends, subject to regulatory approval, to list xStocks for trading on its planned LSE 24 venue in 2027.
This is no longer a hypothetical market measured in a handful of pilots. CryptoSlate has already tracked tokenized stock trading at crypto-scale volumes, while the harder ownership question has become its own market-structure issue because products that resemble shares can come with very different rights. Tokenized stocks can look like familiar equities without giving buyers the same legal position, and the infrastructure beneath them can be just as unfamiliar.
Robinhood is a good example of what that infrastructure may look like in practice. Robinhood Chain has already turned tokenized stocks into assets that can circulate through permissionless crypto markets, but the professional liquidity layer looks much less like an open AMM experiment. 0x says its Stock Token implementation connects applications to professional market makers through RFQ, with USDG as the primary base pair and Tokka Labs as the primary maker participating through that system.
That’s the point where the DWF report’s speculation about real-world assets becomes much more important than the report itself. Mature tokenized assets don’t have to inherit the market design of early DeFi simply because they settle on a blockchain. Tokenized Apple shares have a deep reference market elsewhere, professional firms capable of managing inventory around them, and traders who care about execution quality. Putting that share on-chain won’t suddenly make a passive public pool the natural place to trade it.
For years, the tokenization debate asked whether Wall Street’s assets would move onto crypto’s rails. But a much more important question is appearing behind it: when they get there, whose market structure will they use?
CryptoSlate has already seen the same tension elsewhere in tokenized equities. Markets sold as a way to remove financial middlemen can still depend heavily on old financial infrastructure, including the brokers and custodians holding the underlying shares. One broker now handles the backing for a large share of tokenized equities. The propAMM transition points in the same broader direction from the trading side: blockchains can alter which parts of finance are public without making every intermediary disappear.
The trade is public, but the trading desk isn’t
The easiest conclusion would be that DeFi spent years trying to escape Wall Street and then rebuilt it anyway, but that’s too simple. What crypto may actually be doing is separating two things that were once treated as if they had to travel together: transparency of settlement and transparency of execution.
Blockchains can publicly establish that a trade occurred, transfer the assets, and let those assets move through programmable infrastructure without requiring the market maker’s pricing algorithm to be public. The settlement layer can be open while the execution layer contains private firms competing with one another.
There’s an economic reason for doing this. Professional market makers that can protect themselves from stale prices and traders exploiting old quotes don’t have to build those losses into every price they give ordinary users. Better information and faster repricing can make a private dealer cheaper to trade against than a fully public pool.
The trade-off moves somewhere else. If users stop choosing exchanges and start choosing routers, the router gains much more influence over the market. It decides which firms are allowed to compete, which liquidity sources receive an order, what information accompanies it, how quotes are compared, and how transactions reach the blockchain.
Solana’s own propAMM explainer identified several versions of this problem. The code can be closed, inclusion by aggregators is permissioned, and users can’t always independently verify why one market maker won when several offer equivalent prices. The blockchain can show the trade that happened without showing the full competition that happened before it.
That becomes more important as market making, routing, transaction delivery, and block building begin to touch one another. Blockworks Research has examined the relationship among HumidiFi, transaction-landing system Nozomi, and block builder Harmonic, all associated with Temporal, and found periods when HumidiFi price updates reached Harmonic validators first much more often than other setups. The advantage later disappeared.
The episode is more interesting as a preview of the next DeFi market-structure debate than as an allegation: when several layers can influence execution, what exactly counts as best execution on a blockchain?
Traditional finance has spent decades writing rules around versions of that problem. Best execution, order routing, market access, quote priority, and conflicts between brokers and dealers all exist because the place where an investor presses “Buy” is only the beginning of the transaction. DeFi is rediscovering some of that complexity while rebuilding the system from different pieces.
The difference is that some pieces that historically lived inside the same financial institution can now be separated and placed on public networks. That makes the market more inspectable in some places and less inspectable in others, which is a much more interesting outcome than simply declaring it more or less transparent.
None of this means the original AMM is disappearing. Its weakness is also the reason it will probably survive.
Professional market makers work best when they have some idea what an asset is worth. $SOL has deep markets elsewhere; Apple has a stock exchange; Treasuries have a reference price. Trading firms can look at those markets, calculate a value, hold inventory, and quote around it.
Now imagine somebody creates Token X at 3 a.m. There may be no deep outside market, no dependable reference price, and no professional firm willing to warehouse it. Before anybody can make a sophisticated market, the asset needs a market at all. Public AMMs don’t need to know what Token X is worth: someone just supplies Token X and $USDC, and trading can begin.
That’s why the DWF data is more interesting as evidence of a sorting process than as proof that one design is replacing another. Professional liquidity works especially well for established assets with deep reference markets. Traditional AMMs retain their advantage in the long tail, where permissionless market creation is more valuable than shaving fractions of a percentage point from execution.
Tokenized finance could divide along the same line. Apple shares, Treasuries, $SOL, ETH, and other heavily traded assets are natural territory for sophisticated dealers competing behind routers. Assets without mature outside markets may still depend on public pools willing to trade whatever anyone deposits.
Crypto began with a much grander cultural promise: software would remove the financial middleman. But its trading markets are now producing a more complicated answer. Some intermediaries were products of old infrastructure, while others existed because somebody still has to price risk, hold inventory, and stand ready to trade.
Blockchain technology doesn’t have to eliminate that role to remake the market around it. The rails can be public, settlement can be inspectable, assets can move between applications instead of being trapped inside one institution, and professional dealers can compete over the same order without owning the infrastructure underneath it. The person pressing “Swap” may never know which one won.
The future exchange may be a blockchain everyone can inspect, wrapped around a trading desk almost nobody can see.
