
The thing is, your bank really liked having you as the customer. If you take your money away, now it owes that money to a company managing withdrawals for thousands of people, with someone paid to decide where the reserves should go.
The dollars came back, but they came back with a different owner, and that owner can be a much more demanding creditor.
This is the part of the stablecoin debate that gets lost when everyone starts estimating how many trillions will leave banks. The amount in the bank can stay the same while the bank gets a much worse deal, because a deposit’s value to a bank depends partly on how long the customer will leave it there and what it costs to keep it.
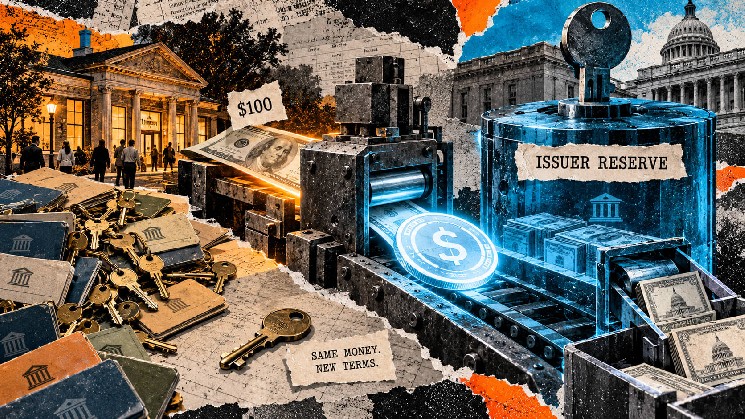
The Bank for International Settlements’ 2026 analysis used a $100 purchase to show how household deposits can return as issuer deposits while making banks’ funding less dependable under regulatory measures.
If banks have to spend more to support that money, some of the cost could eventually reach people taking out loans, including people who don’t even know what a stablecoin is.
Your bank likes you a little boring
The balance in your banking app is money the bank owes you. You have a right to spend it, but the bank doesn’t keep every customer’s balance in a separate pile waiting to be collected. Its assets also include loans repaid over years, while customers can ask for their deposits much sooner.
Banks can create deposits when they make loans, but they still need to fund the payments customers send elsewhere. Keeping a dependable base of deposits helps them do that.
That arrangement works partly because people don’t usually need all their money at once.
Your salary comes in while someone else’s rent goes out, and across enough customers, the bank can plan around a reasonably dependable deposit base. It still needs ready cash for payments, but it doesn’t expect every account to empty on the first of the month.
That comfort has limits, as any bank run shows. Still, many individual balances used for everyday life can be easier to manage than one very large account whose owner can move the whole amount with a single decision. Bankers call the first kind retail funding and the second wholesale funding.
Stablecoin issuers also have promises to keep. If token holders redeem, the issuer needs dollars to pay them, and withdrawing reserves from a banking partner may be part of getting those dollars ready.
The bank can lose the balance even if it’s perfectly healthy, because the issuer’s customers need money somewhere else.
The Fed’s research on stablecoins and bank deposits describes this conversion from scattered household balances into large institutional accounts. It doesn’t make every household loyal or every issuer flighty, but it does explain why adding up all the deposits misses something a bank’s funding team has to think about every day.
The Liquidity Coverage Ratio, under the Basel banking framework, compares assets a bank can readily turn into cash with the net cash outflows it could face during 30 days of stress. Different deposits come with different assumptions about how much might leave.
A bank with $120 million of qualifying liquid assets and $100 million of estimated net outflows has a ratio of 120%. A different mix of customers could push estimated outflows to $110 million while those assets stay the same.
The ratio falls to about 109%, even though nobody has withdrawn anything.
While that’s just back-of-the-napkin math, it shows why banks can’t just shrug and say total deposits haven’t moved. Its estimated cash needs have increased, leaving less spare room above the required buffer.
Depending on the rules it faces, the bank may need more liquid assets or funding it can count on for longer, both of which can cost money.
The dollars don’t disappear when someone buys a Treasury bond
Issuers don’t always leave the money in a bank account. They can buy short-term Treasury bills to back their tokens, earning interest while holding an asset they expect to sell when customers want dollars back.
This adds another person to our $100 example: whoever sells the bill. If the issuer buys an existing Treasury from a nonbank investor, the issuer’s bank balance falls by $100 and the seller’s rises by $100. The money has another owner, but the banking system still has the deposit.
That doesn’t tell us how dependable the new owner’s balance will be, and it certainly doesn’t tell us where they’ll move it next. The only thing it tells us is that counting the issuer’s Treasury purchase as $100 permanently removed from bank deposits skips the person getting paid for the Treasury.
Buying a bill that a bank itself owns produces different accounting. The bank gives up an asset, and the payment can extinguish a deposit liability, reducing both sides of the banking system’s balance sheet.
The bank has also sold a security it might otherwise have kept available for its own cash needs.
Buying newly issued government debt adds a further step because the payment goes to the Treasury’s account, with government spending later sending money back out. That’s different from paying a private investor, so saying “the issuer bought Treasuries” doesn’t explain the whole thing.
BIS General Manager Pablo Hernández de Cos put reserve composition at the center of the banking effects in an August speech. The route the backing takes determines what happens to banks, which is why a forecast for token supply alone can’t tell you how much lending will be lost.
Our example also assumes money reaches the issuer to back new tokens. If you buy existing stablecoins from another holder, your payment goes to that seller, and it doesn’t automatically create a new reserve deposit.
Then there’s the difference between banks collectively and the particular bank you used to pay. Your smaller lender can lose your deposit while the issuer’s larger banking partner gets the replacement account.
The national total looks unchanged, but your old bank still has to find funding or adjust its business.
The receiving bank isn’t obliged to make the same loans to the same people. It has its own customers and lending standards, so money returning somewhere in banking doesn’t guarantee the local business seeking a loan will find its lender just as willing to provide one.
Banks now need to compete with stablecoins
None of this entitles a bank to keep your money cheaply forever. If a stablecoin gives you a payment service your bank doesn’t, moving is a reasonable choice, and protecting the bank’s profit margin isn’t your job.
Banks can compete by paying more interest or improving their own payment services. They can also replace lost deposits with longer-term borrowing, although lenders willing to commit money for longer will want terms that make it worth their while.
The bank then has to decide how much extra cost it can absorb and what that does to the loans it can profitably offer.
The Fed’s study of how banks handled earlier financial competitors looked at adaptation to money-market funds and payment platforms. Stablecoins aren’t the first product to give customers another place to keep transaction money, and banks have options beyond watching the balances leave.
One is to offer some of the technology while keeping the customer as a depositor. CryptoSlate’s reporting on tokenized deposits and bank funding explained that recording a deposit on a blockchain can preserve the customer’s claim on the bank.
However, the sales pitch still has to work for the customer, including whether the product can send money where they actually need it.
Issuing stablecoins is another possibility, but it comes with its own requirements. The Fed’s Sept. 24 proposals would set reserve and risk-management rules for payment stablecoin issuers under its supervision, alongside a process for supervised banks seeking approval for a subsidiary to issue them.
Money committed to redeeming tokens can’t be treated just as ordinary bank funding available on identical terms for a portfolio of long-term loans. Owning the issuer doesn’t make the promise to token holders go away.
The BIS examples show how the accounts can work, but they don’t prove stablecoins have already caused banks to cut lending. Establishing that would take evidence from the banks involved, including how they replaced deposits and what happened to their loan books.
It would also require knowing where buyers got the money, since new dollar demand from abroad needn’t have the same effect as customers moving existing domestic deposits.
The trade-off is worth understanding without defaulting to the banks’ side. Faster payments can be valuable, and banks having to compete harder for customers can be a good thing, even if dependable funding becomes more expensive along the way.
Your $100 can make it back into a bank while the comfortable customer relationship attached to it is gone. The bank now owes someone else, on terms that may require more cash on hand or a better interest rate, and those costs help determine what it can afford to do for the next person asking for a loan.
