
How Ethereum staking balances diverged
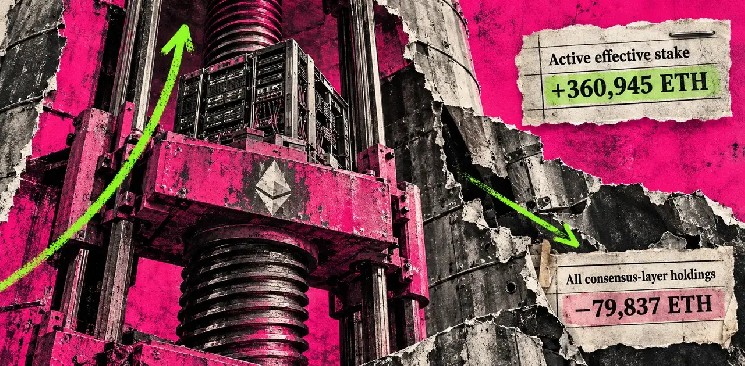
The comparison uses CryptoKeyhole’s daily staking-share series and supply data for the 30 complete UTC days from Oct. 1 through Oct. 30, measured from Sept. 30 close to Oct. 30 close.
Active stake is the effective balance of validators participating in consensus: the amount that counts toward their network weight. The broader consensus-layer measure also includes queued deposits, validators waiting to activate or be paid after exiting, and balances above the effective amount.
Multiplying the provider’s published daily shares by its corresponding supply figures gives the following approximate balances:
These approximate balances are calculated from CryptoKeyhole’s series and rounded to whole $ETH. They inherit its supply methodology, which can include modeled rewards for days whose closing state has not been read. The final row combines several categories; it does not identify each one’s contribution.
About 361,000 $ETH more counted as active effective stake while total consensus holdings fell by about 80,000 $ETH. The combined balance outside the active effective tally contracted enough to accommodate both changes.
A shrinking total $ETH supply does not explain the higher active share in this dataset. CryptoKeyhole’s supply series increased by about 86,137 $ETH across those closes. Its broader consensus-layer share fell from 37.336% to 37.245%, even as active share increased.
The flow measure counts deposit requests in each day’s blocks, including deposits for new validators and top-ups to existing ones. A request does not immediately become active effective stake. Ethereum’s pending-deposit processing and activation rules impose separate steps before that capital can contribute to consensus.
Previously deposited $ETH can become active during October without another deposit or contemporaneous spot purchase. Conversely, an October deposit can remain queued beyond the month.
Withdrawals have their own timing difference. A validator stops contributing active stake before its remaining balance is eventually paid to its withdrawal address. A payment completed in October can thus reflect an exit that affected active stake earlier.
How rewards and payment timing change active stake
Rewards can also increase active stake without a deposit. Ethereum’s compounding validators can retain rewards and raise effective balances up to 2,048 $ETH, while legacy validators have a 32 $ETH effective cap and automatically sweep excess rewards. Whole-$ETH balance adjustments and a buffer further separate rewards earned from effective stake added.
CryptoKeyhole excludes automatic excess-balance reward sweeps from its principal-withdrawn category. It includes full balances paid to exited validators and partial withdrawals requested from the execution layer. Those payments can contain accumulated rewards, making “principal” a category label rather than a calculation of original deposits alone.
Consolidations also require separate accounting. They move existing stake into fewer validators instead of constituting new external deposits. Intermediate changes in active balances and any residual later withdrawal can affect the relevant tallies without representing fresh buying.
Activation and payment timing therefore help explain how the measures can diverge. The aggregate balance changes do not allocate the 360,945 $ETH increase among activation, reward compounding, consolidation effects and other effective-balance adjustments.
The 110,763 $ETH flow deficit also measures different components from the change in the full consensus ledger. The latter includes rewards net of penalties and automatic payouts, so these aggregates alone do not fully reconcile the two.
A deep entry queue still represents earlier commitments
The entry backlog provides another stock of $ETH that must be separated from new deposits. CryptoKeyhole’s closing queue fell from 1,578,359 $ETH on Sept. 30 to 1,226,570 $ETH on Oct. 30, a decline of 351,789 $ETH.
That decline is not a direct measure of activations. New requests, processing and internal queue movements can change the balance along the way. Equally, the exit queue’s fall from 604,304 $ETH to zero does not mean that amount was paid out during the month.
At the finalized epoch timestamped Nov. 2 at 09:52 UTC, CryptoKeyhole reported 1,104,862 $ETH awaiting entry and estimated 19.7 days for a new deposit to be credited. This later snapshot provides context for the backlog; the October comparison uses the closed-day balances above.
A zero exit queue also leaves later payout steps intact. CryptoKeyhole reported a 27.3-hour withdrawability delay after exiting, followed by payment on a withdrawal sweep. Its last complete sweep cycle took 7.1 days; that historical duration is not a guaranteed waiting time for every validator.
CryptoSlate’s October coverage of staking delays distinguished the wait to earn from the stages required to get $ETH back. The month-end figures add a separate lesson: a queue, an active balance and a completed payment describe different points in the same process.
At the other end, Ethereum’s withdrawal rules credit the specified execution-layer address. That payment alone establishes neither an exchange deposit nor a sale.
