
Bills were not a duration vote
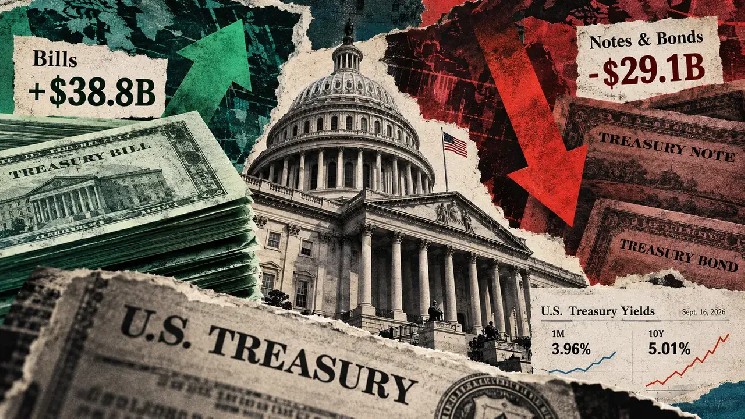
Bills mature within a year, while Treasury notes run from two to 10 years and bonds from 20 to 30 years, according to TreasuryDirect’s maturity definitions. July’s composition was therefore consistent with private demand favoring cash-like government paper over duration, although it cannot show that the same investors directly rotated from one maturity bucket into another.
Market pricing carried the same broad tension during July. From the first to last trading day, the 10-year Treasury yield rose from 4.48% to 4.75%, while the 30-year climbed from 4.97% to 5.27%. The three-month rate edged down from 3.85% to 3.83%. By Sept. 16, 2026, the Treasury curve showed 3.96% at one month and 5.01% at 10 years, a 1.05 percentage-point gap.
The July flows and September curve are separate observations, not a causal chain. Treasury also warns that its monthly long-term holdings data are primarily custody-based, which can obscure an asset owner’s country. The July flow table is not seasonally adjusted, and TIC excludes direct investment.
Bitcoin inherits the rate risk
Research from the Federal Reserve identifies foreign demand as one factor that can affect Treasury term premiums, but the relationship is endogenous and cannot convert one month’s flow into a specific yield move.
Long yields matter through a broader financial-conditions channel. The Fed’s financial conditions framework treats Treasury yields alongside private borrowing rates, equities and the dollar. Higher risk-free returns can raise the opportunity cost of holding a non-yielding asset such as Bitcoin, while tighter credit can reduce the capital available for risk assets.
That mechanism leaves Bitcoin sensitive to duration pressure, but it does not establish that July’s TIC flows drove Bitcoin’s September performance. The cleaner conclusion is that foreign demand returned to the safest, shortest part of the Treasury market while long-term borrowing costs remained elevated. The next sign of a broader improvement would be private foreign accounts returning to Treasury notes and bonds alongside a sustained decline in long yields, not merely another month of bill buying.
