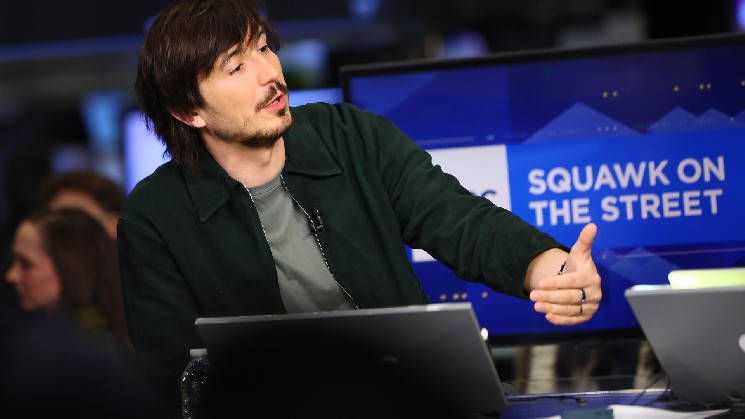

“If it creates a separate financial instrument that holds or references freely transferable shares without changing the issuer’s rights, obligations, or authoritative shareholder record, issuer consent should not be required,” Tenev wrote.
That distinction is where AMC’s Aron and Tenev disagree.
Aron has called Robinhood’s product a “fictitious synthetic equity market” and argued that it could weaken AMC’s ability to raise capital, confuse investors about their rights and create a market bearing AMC’s name without the company’s consent.
Tenev, on the other hand, argued existing markets already allow similar arrangements. Options, unsponsored American depositary receipts and structured products can reference public shares without giving the underlying company control over the product.
He drew a line at products that alter the shares themselves. If a token changes shareholder rights, replaces a company’s official stock ledger or creates new obligations for the issuer or its transfer agent, Tenev said the company should have a say.
“If a product purports to change the rights attached to the underlying shares, replaces the company’s official stock ledger, or imposes new obligations on the company or its transfer agent, the issuer should be involved,” he wrote.
The disagreement matters beyond AMC and Robinhood. Firms are testing several ways to put stock exposure on blockchains, from synthetic products to conventional shares held by custodians and issuer-backed shares recorded directly onchain.
