
Institutions could eventually interact with those products without touching the memecoin market that helped create the activity.
The causal bridge from meme trading to deeper lending liquidity or institutional use remains hypothetical, but moves such as Pump.fun’s Custom Pairs makes that potential connection timely enough to test.
From a memecoin trade to tokenized-asset inventory
Tokenization turns exposure to an equity, exchange-traded fund, or another real-world asset into a transferable blockchain token. Issuance alone doesn’t solve demand, market depth, or collateral utility.
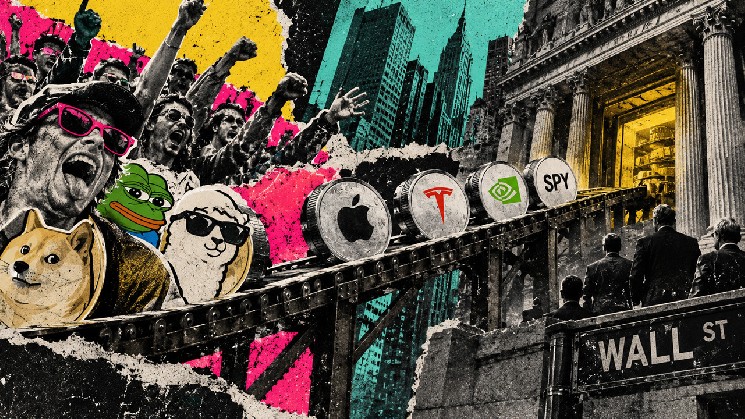
In a market where a meme is quoted in a tokenized stock, the stock token becomes the settlement side of the trade. A buyer may want the meme rather than equity exposure, but entering the pair still creates transactional demand for the tokenized asset and puts more of it into wallets or pools.
Memecoin pairs using tokenized stock tokens on Robinhood Chain generated $217 million in trading volume on Sept. 2. That result shows activity but leaves persistence and migration into other financial products unresolved.
Raydium announced on Sept. 6 a newly issued token to pair with any supported quote token and named LaunchOnSF as the first integration.
The moves suggest custom quote assets are becoming a category feature, so a tokenized stock can become necessary inventory inside a market sought for an entirely different reason, broadening its route to users beyond deliberate equity exposure.
More transactions can spread that inventory across traders and pools, giving liquidity providers and market makers more opportunities to support the asset. Meanwhile, volume and wider distribution remain weak proxies for execution quality.
The next stage depends on whether protocols can safely use the token as collateral and whether borrowers and lenders show sustained demand.
In February, Ondo Finance said its $SPYon and QQQon tokenized ETFs had entered Morpho lending markets on Ethereum.
A tokenized ETF begins as blockchain-based market exposure. Once accepted as collateral, it can support borrowing and other capital-efficient strategies without requiring the holder to sell that exposure.
Flowdesk, stablecoin issuer Agora, and xStocks announced a Morpho strategy that accepts the $AUSD stablecoin and allocates capital to a market using tokenized S&P 500 exposure (SPYx) as collateral.
The vault opened with an $18 million cap, while Flowdesk handles curation, liquidity, and ongoing risk monitoring.
Morpho’s live interface listed over $6.3 million in deposits around Sept. 8 and Sept. 9 and identifies Limitless Frontier Corp. as the operator.
The balance shows real use while also noting the gap between available capacity and deposited capital.
Different users can deepen the same market
A meme trader may acquire a tokenized stock because it is the quote asset for a desired coin, while a liquidity provider may hold both sides of the pair to earn fees.
At the same time, a borrower may keep the stock token for its market exposure while using it as collateral, a vault depositor may care about the yield generated by borrowing demand, and a professional risk manager may focus on caps, oracles, and liquidation routes.
That progression explains how retail speculation could reach institutional infrastructure without requiring institutions to trade memes. Different groups can use the same underlying inventory through different products.
On Aug. 10, xStocks launched five tokenized stocks and ETFs as native spot markets on Hyperliquid’s HyperCore order books. It said full composability on HyperEVM, Hyperliquid’s smart-contract environment, would follow and could include lending, collateral, and structured-product integrations.
If custom pairs spread across launchpads and chains, they could repeatedly introduce tokenized assets to traders and liquidity providers. A broader base of transactions and inventory could make new lending markets, portfolio collateral, and managed strategies more attractive to build. Added utility could then create another reason to acquire the asset.
Transaction counts remain an incomplete measure of liquidity depth, pricing reliability, and holder stability. A tokenized asset also needs dependable minting and redemption, clear legal and eligibility rules, robust price feeds, predictable liquidation mechanics, and enough market depth for lenders to exit collateral without disorderly losses.
Ondo’s tokenized-stock framework connects eligible users to minting and redemption against underlying market exposure, subject to geographic and onboarding restrictions. Gauntlet and Flowdesk add collateral parameters, caps, monitoring, and liquidation design around specific lending products.
If the quote asset is thin, a fast meme rally can produce inventory without producing trustworthy price discovery. If redemption is limited or an oracle fails during volatile trading, lenders face risks that no amount of trade count can offset.
Institutional users need predictable routes into and out of positions alongside visible activity.
Custom pairs would give users a reason to touch tokenized assets and seed the transactions and inventory from which deeper markets might grow. DeFi’s role is to determine whether that activity can be transformed into borrowing capacity, managed exposure, and collateral that remains useful after speculative attention moves elsewhere.
Current evidence shows material stock-token meme trading on Robinhood Chain, a fresh custom-pairs push on Solana, and separate tokenized-equity lending products with real deposits and professional controls.
Memecoins may provide the spark, while redemption, risk management, collateral design, and persistent liquidity will decide whether the result becomes infrastructure.
