
That combination has fundamentally changed negotiating power.
Buyers Have More Power, but Many Still Cannot Afford to Buy
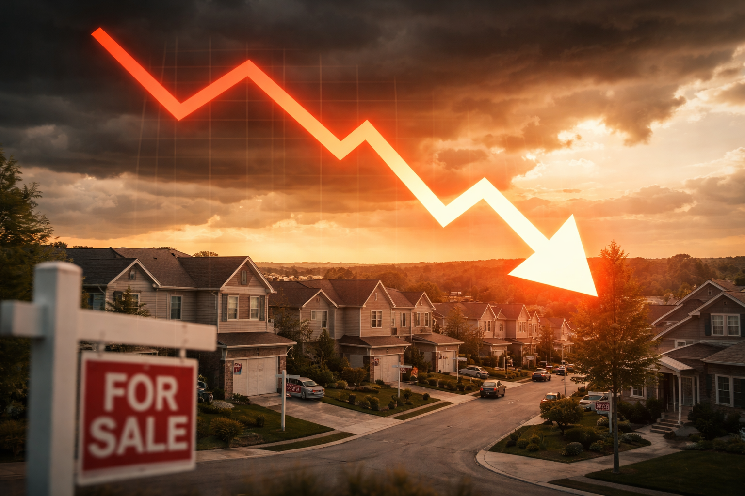
A record buyer’s market would normally suggest strong conditions for home purchases.
This time, the picture is more complicated.
Three in five homes sold in August went for less than their original asking price, while total housing inventory reached its highest level since 2020. Sellers are increasingly cutting prices, offering repairs or helping with closing costs to attract a shrinking pool of buyers.
But elevated borrowing costs continue to keep many households out of the market.
The average 30-year mortgage rate recently climbed toward 6.7%–6.9%, extending the affordability pressure described in Coinpaper’s coverage of mortgage rates near 7%.
High rates are especially painful because home prices remain elevated. The national median sale price was still up roughly 2.2% year over year in August even as demand weakened.
That helps explain why the market can simultaneously favor buyers who are active while excluding millions of potential buyers entirely.
Sun Belt Markets Are Seeing the Biggest Imbalance
The national figure also hides enormous regional differences.
Nashville had 139% more sellers than buyers, followed by Miami at 138% and Houston at 131%.
Eight major metros now have at least twice as many sellers as buyers, including Orlando, Las Vegas, San Antonio, Austin and Dallas.
The shift is particularly striking because the housing market spent years suffering from the opposite problem: too few homes for sale.
The pandemic-era mortgage lock-in effect kept millions of homeowners from moving because they did not want to give up mortgages below 3%–4%.
That effect is now weakening. More owners are listing despite higher rates, while buyer demand remains constrained.
Existing-home sales fell another 2% in August to a 3.98 million annual pace, the lowest in 14 months, while available inventory climbed to 1.62 million homes.
