
“Rate hikes cannot produce oil, expand refining capacity, or repair disrupted supply routes,” he continued. “They reduce demand, investment, employment, and household purchasing power.”
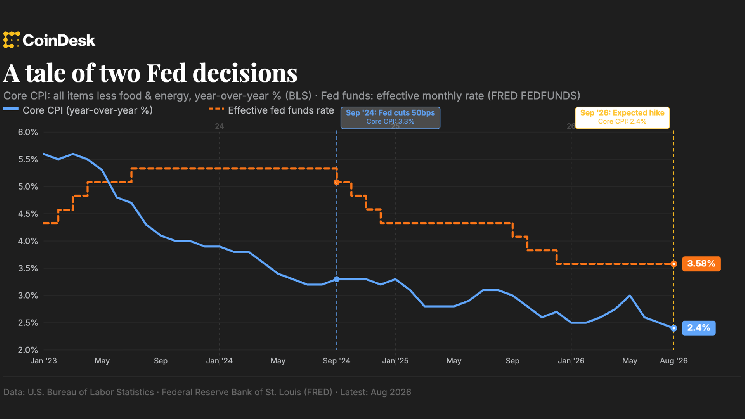
Thorne noted that wage growth has slowed to just 3.1% year-over-year. “There is no demonstrated wage price spiral, no verified second round inflation, and no evidence that the energy shock is becoming embedded.”
“If the Warsh Fed hikes simply to validate Wall Street’s futures market narrative, Warsh’s critique of the Wall of Mirrors and his promise to end forward guidance will not have been worth the paper his Jackson Hole speech was written on,” he concluded.
Inflation may be perkier than core CPI showed
Not all agree with Thorne, of course.
“The [core CPI] gain were heavily in services, said Diane Swonk, chief economist at KPMG. Super core services, she said, were up a particularly hot 0.5% and up 3% year-over-year.
Based on the CPI data, the PCE Index, which is the Fed’s preferred inflation gauge (not CPI), is likely to be higher by 0.4% in August, with core up 0.3%, said Swonk. That would put the annualized pace of core PCE at 3.4% — far more above the Fed’s 2% target than core CPI.
“We now expect three rate hikes by early 2027,” concluded Swonk. “The probability that the vote will be unanimous just rose. That would provide a much needed boost to the Fed’s inflation-fighting credibility, something the bond market is craving.”
