
Brown argued that when someone buys a “passive” index fund, a private company’s committee, not the fund manager, decides what counts as “the market.” However, three firms, MSCI, S&P Dow Jones Indices and FTSE Russell, set the benchmarks that 54% of all long-term fund assets in the United States follow.
$21 trillion is benchmarked to MSCI’s indexes alone.
Brown is calling out that scale as a problem. Index providers, by adding or cutting a single company, force every fund tracking the benchmark to rebalance, which trickles down to individual stocks gaining or losing financial bases without any fund managers or investors involved in those decisions.
The BPI document contends that index providers wear a passive label while making active decisions, with little oversight, as they are not currently regulated as investment advisers.
MSCI’s neutrality faces scrutiny
MSCI has insisted over the years that it is a neutral entity, telling the SEC in 2022 that it “expresses no opinion or view as to whether any market, company, strategy or investment is good or bad.” In 2024, it told congressional investigators that an index “is simply a mathematical calculation” that “does not, and cannot, channel investments.”
Brown pointed to the September 2025 MSCI proposal to remove any company holding at least half its assets in Bitcoin or other digital assets as proof that MSCI makes discretionary decisions.
After pushback, MSCI shelved that plan in January 2026, announcing that it would drop the digital-asset-treasury exclusion criteria, but it would open a broader consultation on “non-operating companies” instead.
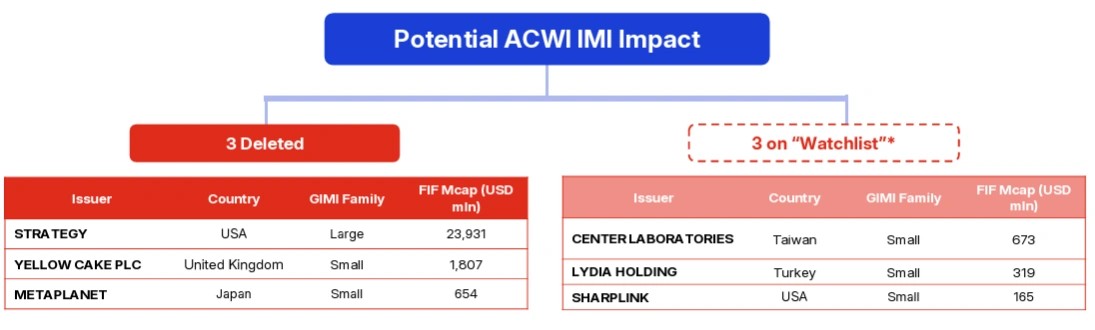
That broader consultation arrived in August 2026, laying out a methodology that, when applied to the ACWI IMI index using May 2026 data, cut Strategy, UK uranium holder Yellow Cake and Japan’s Metaplanet.
Three more, including Ethereum treasury firm SharpLink, would land on a public watchlist, as Cryptopolitan reported.
Brown made the same point that Strategy made in its refusal of MSCI’s “operating assets” category, arguing that it is not defined under U.S. GAAP or IFRS.
Strategy called the proposal “misguided” and a “pretext for targeting Digital Asset Treasury Companies,” while arguing the hit is minor because MSCI GIMI-linked funds hold only about 3.1% of its shares.
The paper also pointed to metadata from the public PDF for the August 2026 consultation as “concrete evidence of continuity and potentially shared purpose between the two consultations” and “warrants asking whether its broader language carried forward the earlier intentional effort to remove those companies.”
Why BPI is asking for Congress action
Brown is calling on Congress to scrutinize what it describes as discretionary exclusions, citing the historical precedent set when lawmakers once examined MSCI’s index decisions.
A 2023 House select committee investigation faulted MSCI and BlackRock over investments in blacklisted Chinese firms.
A follow-up report in 2024 claimed MSCI indexes channeled $3.7 billion into Chinese entities accused of human rights abuses and military ties.
Brown’s remedy is a presumption of inclusion for lawful, liquid, investable equities in broad-market benchmarks, with any values-based screens moved to clearly labeled opt-in indexes.
MSCI says the comment period closed September 30, with results expected on or before October 16 and any changes folded into the November 2026 index review. It stresses that no change is guaranteed.
