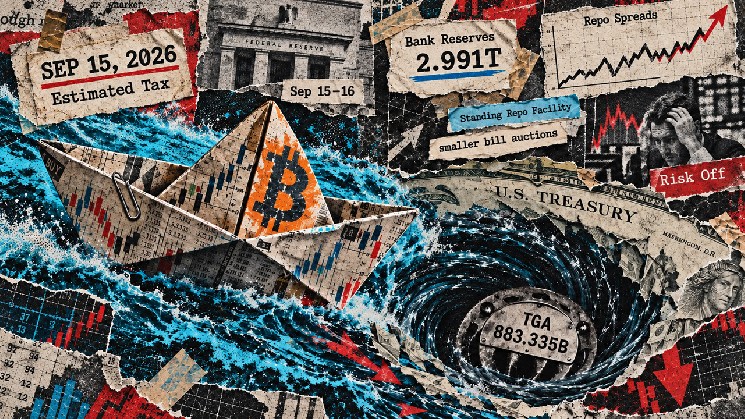

Those are averages, not Wednesday’s snapshot. The separate September 9 levels were about $3.037 trillion for reserves and $843.705 billion for Treasury cash.
How US tax payments could affect Bitcoin liquidity
The accounting mechanism is straightforward: tax payments move balances from commercial banks’ reserve accounts into the Treasury’s account. Treasury spending moves funds back to recipient banks. Other things equal, incoming taxes reduce reserves, while outgoing government payments replenish them.
That can matter for short-term financing, including repo markets where cash is borrowed against securities. The New York Fed’s account of September 2019 describes how a temporary reserve decline, Treasury settlements and a corporate tax date combined with a spike in repo rates. It is a historical example of the mechanism, not evidence that this Tuesday will repeat it.
Several forces can cushion the transfer. In its August 5 refunding statement, Treasury anticipated September reductions in shorter-dated bill auction sizes because of mid-month tax receipts. Less bill borrowing could partly offset cash absorption relative to unchanged issuance. The size of that offset depends on actual borrowing and spending.
The Fed also plans for seasonal reserve demand. Its May 2026 balance-sheet report says reserve-management purchases accommodate fluctuations such as tax dates and adjust to the reserve outlook. The New York Fed describes the Standing Repo Facility as a backstop supplying eligible institutions with temporary cash against securities to limit upward funding pressure.
For Bitcoin investors, the possible effect runs through financing conditions and appetite for risk.
BIS research finds that stablecoin market capitalization declines after US monetary tightening. That supports broader sensitivity to monetary conditions, not a measured Bitcoin response to this tax deadline.
The useful signal is therefore whether short-term funding spreads widen relative to Fed-administered rates as taxes settle. Rising spreads would be consistent with funding pressure without proving taxes caused it; stable funding would weaken that interpretation. Tuesday’s calendar creates a test, while spending, bill supply and Fed liquidity tools help determine the result.
