
The stablecoin debate in Washington is increasingly becoming a fight over a single question: who gets to keep deposit insurance on-chain?
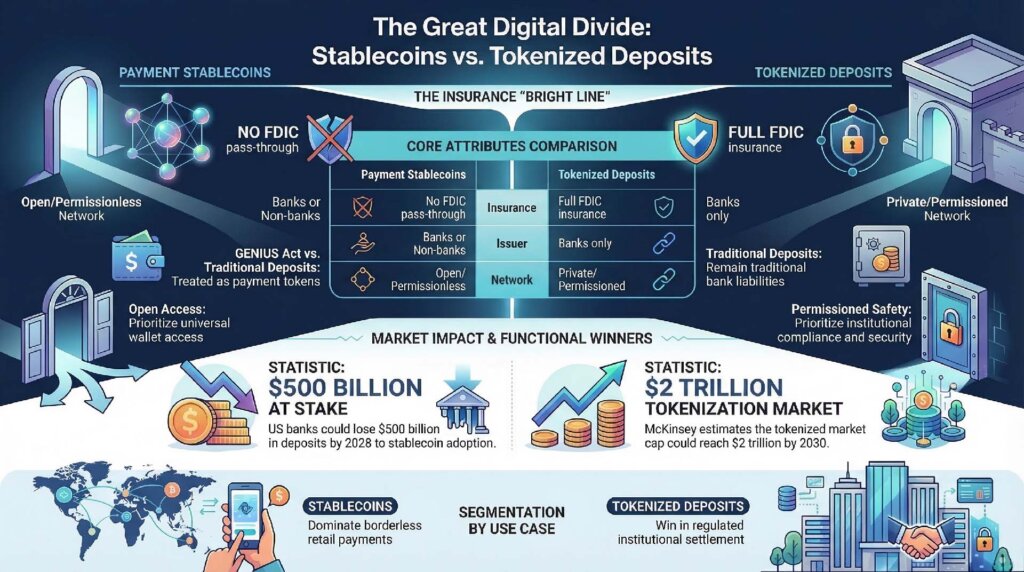
FDIC Chair Travis Hill signaled that payment stablecoins under the GENIUS Act should not qualify for pass-through insurance, while tokenized deposits that meet the legal definition of a deposit would retain the same insurance treatment as traditional bank accounts.
That distinction may prove decisive.
If banks can offer on-chain dollars that preserve deposit insurance while stablecoins cannot, the competitive balance shifts. Stablecoins may still dominate open networks, but banks would retain the core advantage that has always anchored the financial system: insured money.
In that scenario, the stablecoin battle is no longer just about technology or distribution. Whether users prefer open, programmable dollars without insurance or bank-issued tokens that carry the full weight of the existing safety net will be the deciding factor.
In a Mar. 11 speech at the ABA Washington Summit, Hill said the agency plans to propose that payment stablecoins subject to the GENIUS Act are not eligible for pass-through insurance.
In the same section of the speech, he said the FDIC also plans to clarify that tokenized deposits that satisfy the statutory definition of a deposit should receive the same regulatory and deposit insurance treatment as non-tokenized deposits.
Hill also said the agency wants to comment on how existing pass-through rules should apply to tokenized deposit arrangements involving third parties.
The FDIC Chair’s speech effectively sketches a two-tier map of on-chain dollars.
Under that map, payment stablecoins can be regulated and widely used, yet would lack federal insurance marketing rights and, if Hill’s proposal sticks, would not get pass-through insurance.
On the other hand, tokenized deposits remain within the legal category of bank deposits when they qualify, which means they can retain the core advantage of bank money: access to the existing deposit-insurance regime.
This divide feeds into the broader legislative fight over the Clarity Act in Washington, where banks and crypto firms are clashing over whether stablecoins should be allowed to offer yield.
Same blockchain rails, different legal reality
This is part of a broader regulatory thaw. In March 2025, the FDIC said FDIC-supervised institutions may engage in permissible crypto and digital asset activities without prior approval, provided the risks are appropriately managed.
In 2025, the FDIC also withdrew from several interagency crypto statements, including one that had suggested public distributed-ledger activity was likely inconsistent with safe and sound banking.
Then, in December 2025, the FDIC proposed an application framework for FDIC-supervised banks that want to issue payment stablecoins through subsidiaries under GENIUS.
In March 2026, the FDIC, the Fed, and the OCC also clarified that tokenized securities generally receive the same capital treatment as their non-tokenized counterparts.
Put together, those moves amount to a much clearer path back into blockchain-based finance for banks.
The US is now separating on-chain dollars into at least two buckets.
Payment stablecoins are designed for payment and settlement, can be issued by banks or nonbanks under GENIUS, and are attractive because they can run on open blockchain networks.
Hill is drawing a bright line around insurance.
Tokenized deposits fall under traditional deposit regulation when they meet the deposit definition, which gives them a different legal footing. The competition becomes stablecoins versus bank money made portable on-chain.
The banking industry’s concern is concrete. A February 2026 New York Fed staff report argued that stablecoins can erode banks’ deposit franchises and also transmit liquidity stress into the banking system, forcing partner banks to hold more reserves and potentially reducing lending.
Standard Chartered estimates said US banks could lose about $500 billion in deposits by the end of 2028 if stablecoin adoption accelerates.
Hill’s distinction offers banks a way to answer stablecoins with a form of on-chain money that still counts as bank funding.
What tokenized deposits look like today
On Jan. 9, BNY said it had taken the first step in a strategy to tokenize deposits by enabling an on-chain, mirror representation of client deposit balances on its Digital Assets platform.
BNY also made clear what kind of product this is: it runs on a private, permissioned blockchain, begins with collateral and margin-workflow use cases, and represents participating clients’ existing demand-deposit claims against the bank.
The likely near-term winner for tokenized deposits is institutional settlement.
This development sits within a growing market for tokenized finance. McKinsey estimates tokenized market capitalization could reach around $2 trillion by 2030 in its base case, with a range of $1 trillion to $4 trillion, excluding stablecoins to avoid double-counting.
McKinsey also identifies cash and deposits among the likely front-runners.
At the same time, an IMF paper from March 2026 found that shocks to stablecoin demand can push down short-term Treasury yields, weaken the US dollar, and spill over into crypto and equity markets.
The form of digital dollars is becoming a macro-relevant market infrastructure.
What stablecoins still have
New York Fed research argues that the real edge of stablecoins lies in their use on global, open-access, permissionless systems.
The same research says the stablecoin market capitalization recently exceeded $260 billion and that annual organic stablecoin transaction volume rose from $3.29 trillion in 2021 to $5.68 trillion in 2024.
Stablecoins still have distribution, reach, and composability advantages that bank tokens may struggle to match, especially if bank products launch first in private or permissioned environments.
A second New York Fed staff report, published in February 2026, provides a framework for understanding the endgame. It found that the optimal outcome depends on regulatory costs and bank incentives.
The bull case for banks and tokenized deposits assumes that Hill’s proposal becomes final substantially as described.
More banks would launch tokenized-deposit products, and these tokenized deposits would become the preferred on-chain cash leg for regulated tokenized securities and funds by combining programmability with deposit status and existing compliance infrastructure.
That outcome is strengthened by the Mar. 5 capital-neutral treatment for tokenized securities and by recent bank product launches, such as BNY’s.
The bull case for stablecoins assumes the insurance distinction weighs less than network effects.
Stablecoins keep winning where universal wallet access, composability, 24/7 transferability, and cross-border use dominate.
Banks still participate, but through stablecoin subsidiaries under GENIUS rather than through deposit-token products, especially if tokenized deposits stay mostly permissioned and institution-only.
The market segmentation ahead
If both stablecoins and tokenized deposits can move on-chain, with only one category keeping ordinary deposit treatment, the market may start segmenting by function.
Open, borderless, internet-native payments may lean toward stablecoin-heavy solutions. Institutional settlement, collateral movement, and regulated tokenized-asset markets may tilt toward tokenized deposits.
Hill described a forthcoming proposal and said the FDIC is interested in comments, especially on the stablecoin pass-through issue and on tokenized-deposit arrangements involving third parties.
Hill tied deposit treatment to whether the product actually satisfies the statutory definition of a deposit, and the FDIC still wants comment on third-party structures. The design risk is real.
Banks can compete by keeping deposit status on-chain. Stablecoins may dominate open networks, and tokenized deposits may dominate regulated settlement.
The outcome depends on whether the insurance advantage outweighs the network advantage, and whether banks can build deposit products that work across the same open systems that stablecoins already operate in.
