After the New York Times reported yesterday that Nvidia CEO Jensen Huang had a second affair, and the Wall Street Journal reported that his board was preparing to fire him, concerns about Oracle and its reliance on the US chip giant have soared.
Oracle lost $10 billion in market capitalization during after-hours trading yesterday alone, adding to losses for common shareholders that now exceed 10% over the past month and 35% year-to-date.
On October 28, Oracle pledged to cap new stock and bond sales at $20 billion through fiscal 2030, excluding refinancing. On November 2, it agreed to sell 86 million new shares for $10 billion and priced $10 billion in bonds.
That committed the entire four-year budget in one day.
As anyone who starts maxing out their credit, as Oracle is doing with its massive bond offerings, knows, borrowing typically becomes more expensive.
The higher US Federal Reserve benchmark interest rate hasn’t helped, either.
Oracle’s rising borrowing costs
This month, Oracle has had to offer bond traders much more generous coupons to sell its corporate bonds than it did with offerings just nine months ago.
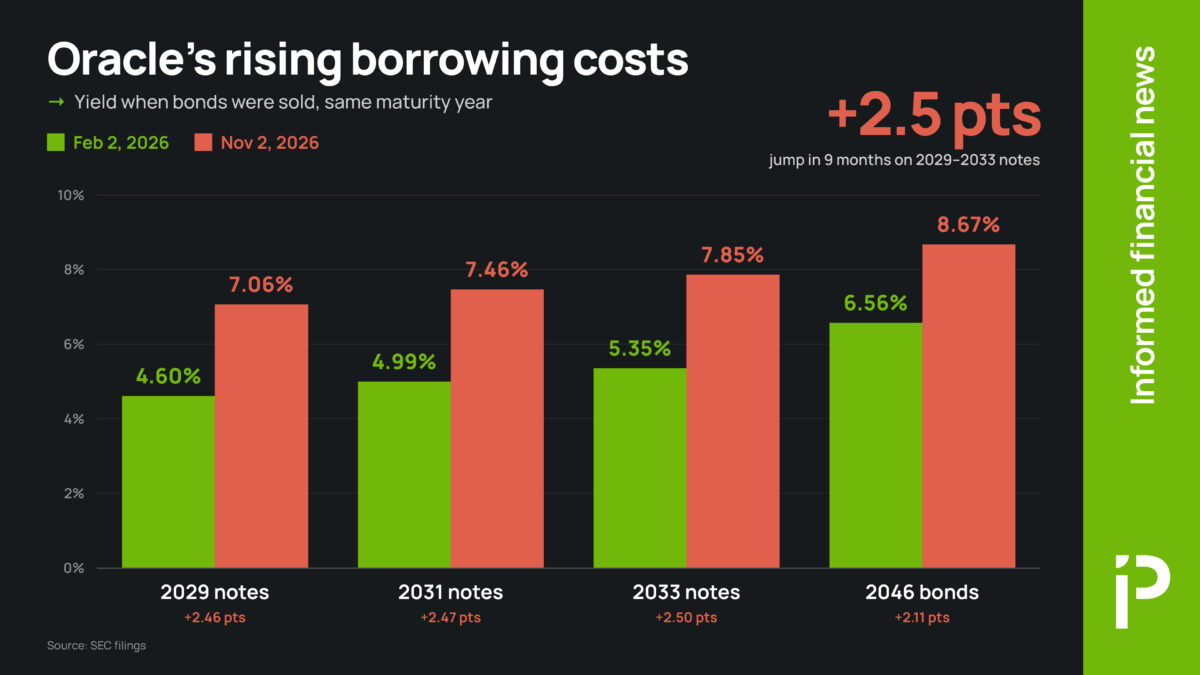
In February, Oracle sold 2029 notes with a yield (technically, yield to maturity) of 4.6%. In November, the company had to sell bonds with the same maturity year at a 7% yield.
Having to raise the yield on corporate bonds is definitely not a good sign.
Higher yields on US Treasury bonds account for part of the increase, but Oracle’s bond premium over Treasuries has widened from 0.95 to 2.40 percentage points—a clear move in the wrong direction.
For Oracle’s 2046 maturity bonds, yield to maturity rose from 6.56% in February to 8.67% in November.
Most concerningly, traders are beginning to speculate that Oracle could default on the debt it is amassing. Oracle’s five-year credit default swaps traded near 305 basis points last week, up 5x from 58 a year earlier.
Credit default swaps forecast AI bankruptcies
More bad news from Nvidia could push Oracle into ‘junk’ territory
Fresh setbacks in the AI industry and rising borrowing costs have investors watching for a possible Oracle downgrade to “junk,” by a credit ratings agency—that is, to non-investment-grade status.
S&P already rates Oracle just one notch above junk, at “BBB-.”. Moody’s and Fitch rate Oracle two notches above junk, though Moody’s has a negative outlook on the company.
Any of the three independent ratings agencies could downgrade Oracle at any time.
In July, when S&P Global Ratings lowered Oracle’s credit rating to BBB-, analysts projected leverage in the mid-4x range for fiscal 2027. Mid-4x is well above the company’s preferred mid-3x threshold for considering a credit rating upgrade.
With a negative outlook from Moody’s, a leverage ratio that S&P considers too high, and a wave of negative news from Nvidia this week, Oracle’s falling stock chart seems to point to an obvious trend.
More bad news for an AI giant
Oracle’s situation keeps worsening. Microsoft itself is winding down its rentals of Oracle AI compute.
Oracle’s OpenAI data center in New Mexico also faces an “open-ended” permit delay (a euphemism for “indefinite”).
That site, Project Jupiter, has had a terrible few days.
On Monday, state regulators blamed the permitting delay on the project’s power developer missing procedural deadlines. On Tuesday, Doña Ana County voted to warn the project’s backers that they may be in breach of contract—the county’s second warning within a month.
Buildings already constructed at Oracle’s data center site have no power.
Making up for lost revenue while paying to maintain empty buildings is clearly putting further strain on Oracle’s already stretched balance sheet.
Could news about Nvidia’s CEO be the straw that breaks Oracle’s back?
Oracle’s revenue mix is poor. Indeed, a single company, OpenAI, contributes roughly halfof its revenue backlog.
S&P analysts were blunt in their warning: “Oracle’s AI strategy carries material credit risks given the aggressive spending and uncertain path to positive cash flow.”
Oracle countered: “Demand for [Oracle’s] AI infrastructure remains strong, including for earlier-generation GPUs.”
S&P said it could downgrade Oracle again if the company’s leverage ratio is set to remain above 4.5x, or if achieving positive free cash flow by fiscal 2029 begins to appear out of reach.
As of Wednesday, a thinly traded Polymarket contract put the chance of Moody’s or S&P analysts downgrading Oracle to junk by June 30, 2027 at about 36%.
In July, S&P called an upgrade “unlikely over the next two years.”